
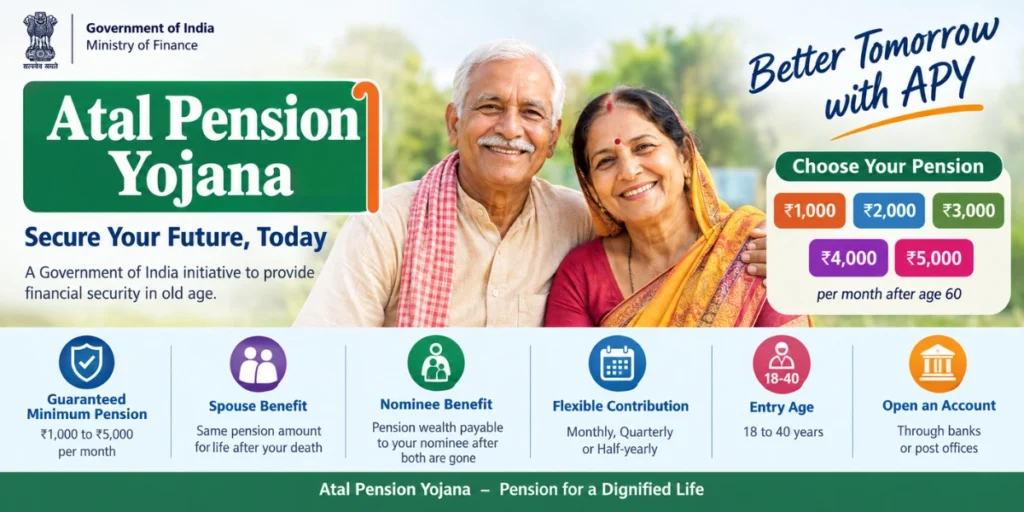
Atal Pension Yojana (APY) is a Government of India-backed pension scheme designed primarily to provide a guaranteed minimum monthly pension during old age, particularly for workers in the unorganised sector. The scheme is administered by the Pension Fund Regulatory and Development Authority (PFRDA). It was introduced in 2015 as part of the government’s effort to expand social-security coverage.
Under APY, eligible subscribers contribute regularly until they reach 60 years of age and can choose a guaranteed minimum pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000 per month.
What is Atal Pension Yojana?
Atal Pension Yojana is a voluntary and contribution-based pension scheme. A person joining the scheme selects a pension slab and makes contributions according to their age at entry, chosen pension amount and payment frequency.
After the subscriber reaches 60, the selected minimum pension is payable for life. Following the subscriber’s death, the spouse is entitled to the same pension amount for life. After both the subscriber and spouse have died, the accumulated pension wealth is payable to the nominee according to the applicable APY rules.
Key Features of Atal Pension Yojana
Some important features of APY are:
- Government-guaranteed minimum pension after 60 years
- Five pension options: ₹1,000 to ₹5,000 per month
- Entry age between 18 and 40 years
- Savings bank or post-office savings account required
- Contributions can be made monthly, quarterly or half-yearly
- Contributions are generally collected through auto-debit
- Spouse receives the same pension after the subscriber’s death
- Pension wealth is returned to the nominee after the death of both subscriber and spouse
- APY is administered by PFRDA
- The scheme is available through participating banks and post offices.
Atal Pension Yojana Eligibility
To open a new APY account, an applicant generally needs to meet these conditions:
- The applicant must be an Indian citizen.
- The applicant must be between 18 and 40 years of age.
- The applicant must have a savings bank account with a bank or a savings account at a post office.
- Since 1 October 2022, an individual who is or has been an income-tax payer is not eligible to open a new APY account.
Existing APY subscribers who joined on or before 30 September 2022 are not affected by the subsequent income-tax-payer eligibility restriction and can continue their accounts subject to the scheme rules.
Atal Pension Yojana Pension Amount
| Pension Option | Monthly Pension After 60 |
|---|---|
| Option 1 | ₹1,000 |
| Option 2 | ₹2,000 |
| Option 3 | ₹3,000 |
| Option 4 | ₹4,000 |
| Option 5 | ₹5,000 |
The pension amount selected determines the required contribution. Generally, joining at a younger age requires a lower contribution because the subscriber has a longer contribution period.
Atal Pension Yojana Contribution
The contribution under APY depends mainly on:
- Age when joining
- Pension amount selected
- Contribution frequency
For example, according to the official APY contribution table, an 18-year-old choosing a ₹5,000 monthly pension option has a prescribed contribution of ₹210 per month. For the ₹1,000 pension option at age 18, the monthly contribution is ₹42.
The contribution can be paid through monthly, quarterly or half-yearly auto-debit. Therefore, applicants should maintain sufficient funds in their linked account around the applicable debit period.
How to Open an Atal Pension Yojana Account
You can generally enrol in APY through a participating bank or post office.
Offline APY Registration
- Visit the bank branch or post office where you have your savings account.
- Ask for the Atal Pension Yojana registration/enrolment form.
- Enter your personal and account details.
- Select your desired pension amount.
- Provide nominee and spouse details as required.
- Submit the completed form.
- The bank/post office will process the APY registration.
- Contributions will subsequently be deducted according to the selected frequency.
PFRDA also provides online onboarding options through eAPY, while availability of online registration can depend on the participating institution.
APY Contribution Frequency
Subscribers can choose from three contribution frequencies:
- Monthly
- Quarterly
- Half-yearly
The contribution is normally collected automatically from the subscriber’s savings bank or post-office savings account.
Also Read- PM Kisan Yojana || PM Awas Yojana List
Atal Pension Yojana Benefits
APY provides three major benefits.
1. Guaranteed Minimum Pension
After reaching 60 years, the subscriber receives the selected minimum pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000 per month for life.
2. Pension for Spouse
After the subscriber dies, the spouse is entitled to receive the same pension amount for life, subject to the APY rules.
3. Pension Wealth for Nominee
After the death of both the subscriber and spouse, the nominee receives the applicable pension wealth. The official APY table specifies corpus amounts corresponding to the selected pension slab, ranging from ₹1.7 lakh for the ₹1,000 pension option to ₹8.5 lakh for the ₹5,000 pension option.
What Happens If the Subscriber Dies Before 60?
APY has provisions dealing with the subscriber’s death before attaining 60. Depending on the circumstances and applicable rules, the spouse can have an option to continue contributing to the APY account until the subscriber would have reached 60, or the accumulated pension wealth can be dealt with according to the applicable scheme provisions.
Therefore, subscribers should check the current APY rules with their bank or PFRDA when such a situation arises. PFRDA’s official notifications specifically include provisions concerning the spouse’s option when the subscriber dies before 60.
Can Income-Tax Payers Join APY?
A person who is or has been an income-tax payer is not eligible to open a new APY account from 1 October 2022.
However, people who had already joined APY on or before 30 September 2022 can continue their accounts even if they are income-tax payers.
Atal Pension Yojana Tax Benefits
APY has provisions concerning income-tax benefits, and PFRDA lists a specific Gazette notification dated 19 February 2016 regarding income-tax benefits under APY.
Because tax rules can change, taxpayers should check the current Income Tax Department provisions or consult a qualified tax professional before claiming a deduction.
Atal Pension Yojana Withdrawal
APY is intended primarily as a long-term pension scheme, with the normal pension benefit beginning after the subscriber reaches 60.
Premature exit is subject to the applicable APY rules and is not equivalent to freely withdrawing the account like an ordinary savings account. Subscribers considering early exit should confirm the current rules with their bank, post office or PFRDA.
How to Check APY Account Details
Subscribers can generally obtain information about their APY account through the bank or post office handling the account. Depending on the service available through the institution, subscribers may also receive account-related information through digital channels.
Keep your PRAN (Permanent Retirement Account Number) and registered mobile details safely available for account-related services.
Atal Pension Yojana and the Unorganised Sector
One of the major objectives of APY is to extend pension coverage to people who may not have access to a conventional employer-sponsored pension.
The scheme is particularly relevant to workers in the unorganised sector, although eligibility is based on the scheme’s prescribed conditions rather than simply on occupation.
APY Administration
The Pension Fund Regulatory and Development Authority (PFRDA) administers APY under the broader pension-system framework. The scheme is implemented through public-sector banks, private banks, regional rural banks, small finance banks, cooperative banks, payments banks and the Department of Posts.
Latest Atal Pension Yojana Update
APY continues to have significant participation across India. In April 2026, PFRDA announced that the scheme had crossed 9 crore gross enrolments, with more than 1.35 crore enrolments during FY 2025–26.
Important Points Before Joining APY
Before opening an APY account, remember:
- You must satisfy the 18–40 age requirement.
- New applicants who are or have been income-tax payers are not eligible.
- You need an eligible savings account.
- Your contribution depends on your age and selected pension.
- Contributions continue until age 60 for normal pension benefits.
- Auto-debit requires adequate balance in your account.
- The pension is a minimum guaranteed amount, not an inflation-linked pension.
- Keep your nominee and spouse information updated.
- Check the latest rules before making decisions about premature exit.
Atal Pension Yojana FAQs
What is the maximum pension under APY?
The maximum guaranteed minimum pension available under APY is ₹5,000 per month after the subscriber reaches 60 years.
What is the minimum age for APY?
The minimum entry age is 18 years. The maximum entry age is 40 years.
Can an income-tax payer open a new APY account?
No. From 1 October 2022, a person who is or has been an income-tax payer is not eligible to open a new APY account.
Can APY contributions be paid quarterly?
Yes. APY allows monthly, quarterly and half-yearly contribution frequencies.
Does the spouse receive a pension?
Yes. After the subscriber’s death, the spouse is entitled to the same pension amount for life, subject to APY rules.
What happens to the money after both subscriber and spouse die?
The applicable pension wealth is payable to the nominee according to the APY provisions.